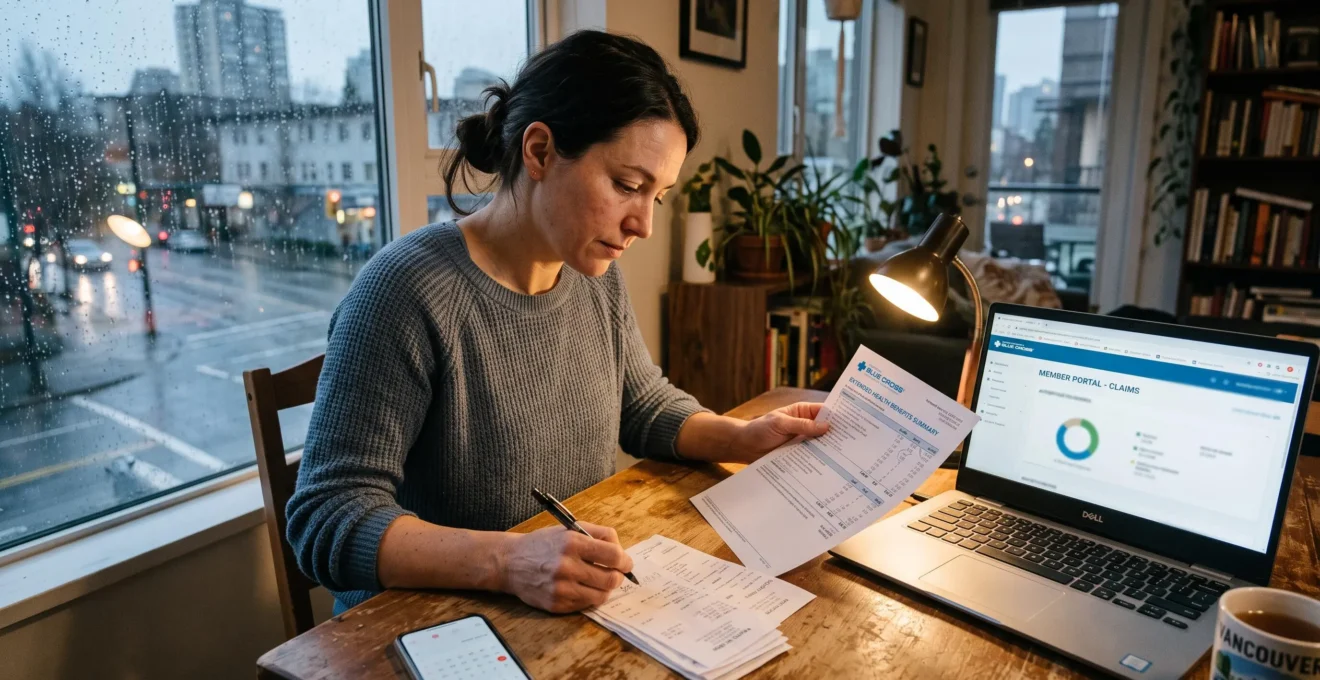
A workplace benefits plan can look generous on paper while delivering surprisingly little value in practice. For employees across Metro Vancouver, the problem is often not a lack of coverage but uncertainty about which services qualify, how much remains available, and when claims must be submitted.
If your plan has CAD $500 in potentially usable coverage remaining, that amount represents an opportunity rather than a guaranteed cash entitlement. You generally need eligible expenses, appropriate providers, and valid claims to receive reimbursement. There is no verified evidence here that every Vancouver employee loses CAD $500 annually.
The practical solution is to examine your actual policy, identify services you genuinely need, coordinate any second insurance plan, and book appointments early enough to meet your coverage deadlines. This approach works whether you have massage therapy benefits, mental-health coverage, an employer assistance program, or a separate wellness spending account.
It also prevents a costly misunderstanding: a benefit that appears available in your insurer’s app may still have practitioner restrictions, per-visit limits, or a submission deadline that changes what you can realistically recover.
How to get more value from your Vancouver wellness benefits
- Check your annual maximums, remaining balances, eligible practitioner types, coverage periods, and claim deadlines before booking.
- Use coordination of benefits where eligible, and verify receipts before submitting claims to reduce preventable rejections.
- Schedule appropriate care throughout the coverage year while combining formal benefits with affordable ways to recover from work stress.
- Why Do Vancouver Employees Underuse Wellness Benefits Even When They’re Stressed?
- How to Audit Your Vancouver Wellness Benefits in 20 Minutes Using a 1-Page Checklist
- Massage or Therapy: Which Wellness Benefit Choice Makes More Sense in Vancouver if You Sit All Day?
- The Claim Mistake That Gets Vancouver Wellness Benefits Rejected After 3 Weeks
- When Should You Book Wellness Appointments in Vancouver to Avoid a 6-Week Waitlist?
- The Perk Trap That Makes Vancouver Employees Accept ‘Wellness’ While Workload Stays Toxic
- Why Does Mountain Time Recover Vancouver Workers Faster Than Staying ‘Offline’ at Home?
- How Can Vancouver’s Coastal Mountains Reduce Work Stress Without Taking Full Days Off?
Why Do Vancouver Employees Underuse Wellness Benefits Even When They’re Stressed?
Vancouver employees can leave workplace wellness benefits unused because they misunderstand their coverage limits, forget their plan’s renewal date, or book practitioners who do not meet reimbursement requirements. Appointment availability, commuting demands, and family responsibilities add practical barriers. The solution begins by separating benefits that are genuinely exhausted from benefits that remain available but poorly understood.
One common mistake is assuming every benefits plan resets on January 1. Some plans operate on calendar years, while others follow different coverage periods. Spending accounts may also have separate allocation, carryover, and expiry rules. The relevant dates are those stated in your employer’s specific plan documents.
Another problem is confusing an annual maximum with a per-visit reimbursement limit. A plan might advertise an amount for massage therapy, but that figure alone does not establish whether the insurer will reimburse an entire appointment, impose a smaller visit limit, or require you to pay a deductible.
Practitioner eligibility adds another layer of uncertainty. An employee might assume massage therapy is excluded when the actual restriction concerns professional credentials. Conversely, a service described as therapeutic by a clinic is not automatically reimbursable.
Three questions help distinguish misunderstanding from genuinely exhausted coverage:
- Do you know your remaining annual maximum for each relevant service category?
- Do you know whether reimbursement is limited per appointment or subject to a deductible or percentage?
- Do you know which practitioner credentials and claim documents your insurer requires?
If the answer to any question is no, the displayed balance is not yet a reliable estimate of what you can recover.
For employees managing long commutes, childcare, or unpredictable working hours, even covered appointments can become difficult to organize. Leaving the decision until the end of a coverage period compounds those practical barriers.
Extended health insurance and wellness spending accounts are not interchangeable. An insurer may adjudicate massage and counselling expenses under defined categories while an employer-funded lifestyle account follows a different list of allowable purchases and deadlines. Carryover is plan-specific and should never be assumed.
Once the dates, restrictions, and eligible services are clear, you can move from guessing about your coverage to planning how to use it.
How to Audit Your Vancouver Wellness Benefits in 20 Minutes Using a 1-Page Checklist
A useful benefits audit starts with your plan booklet and member portal, not with a clinic’s advertised insurance acceptance. Record each relevant annual maximum, the amount already used, per-visit restrictions, practitioner requirements, and claim deadline. Then check whether a second benefits plan or separate spending account could cover eligible costs. The result is a practical appointment budget.
Set aside roughly 20 minutes and open your employer’s benefits booklet, the insurer’s online account, and any separate wellness spending account documentation. Create a one-page worksheet with the categories you might genuinely use.
For each category, record the coverage period, annual limit, remaining balance, deductible, reimbursement percentage, appointment cap, and eligible credentials. If a figure is missing, mark it for confirmation rather than treating it as unrestricted coverage.
Also look for categories administered outside the main extended-health portal. A lifestyle spending account or employee assistance program may operate through an employer-specific provider and might not appear alongside massage or physiotherapy balances.
One particularly valuable step is checking whether you have coverage under two plans. An employee may be insured through their own workplace while also appearing as a dependant under a spouse’s plan.
According to Canada Life’s explanation of coordination of benefits, an employee’s own workplace plan normally pays first. Remaining eligible expenses can then be submitted to the secondary insurer. Combined payments cannot exceed 100% of the original eligible expense, and full reimbursement is not guaranteed.
For example, suppose an eligible appointment costs CAD $120. In an illustrative scenario, the primary plan reimburses CAD $80 and the secondary plan reimburses another CAD $40. The employee’s eligible expense would then be fully reimbursed. Actual payment depends on both policies and their coordination rules.
To estimate appointment capacity, divide your remaining eligible reimbursement allowance by the amount your plan would pay per visit, then compare that result with provider availability and the money you can afford to pay upfront. Simply dividing an account balance by a clinic’s full price can misstate the number of covered sessions.
Your 5-step benefits audit checklist
- Retrieve your current policy: save the benefits booklet or member-plan summary and record its coverage period.
- Build a category balance sheet: write down the annual maximum, amount used, and remaining allowance for each relevant benefit.
- Verify claim conditions: document eligible practitioner credentials, reimbursement limits, deductibles, and submission deadlines.
- Check additional coverage: record any secondary benefits plan, wellness spending account, and available employer assistance program.
- Create a booking plan: choose eligible services you need, estimate your reimbursable amount, and put appointment and claim reminders on your calendar.
With the numbers established, the next decision is which type of care deserves your available time and reimbursement allowance.
Massage or Therapy: Which Wellness Benefit Choice Makes More Sense in Vancouver if You Sit All Day?
For Vancouver desk workers, massage therapy or physiotherapy may be relevant to physical discomfort, while counselling or psychological services may better address persistent stress, anxiety, or emotional exhaustion. The right option depends on your symptoms and an appropriate clinical assessment, not simply which benefit has money remaining. Separate insurance categories, practitioner rules, and employer assistance programs can affect the financial choice.
Hours spent sitting can coincide with neck stiffness, shoulder discomfort, or recurring back pain. Depending on the problem, a qualified physiotherapist may assess movement and function, while registered massage therapy may be considered for muscular discomfort. Chiropractic care is another possible plan category, subject to clinical appropriateness and individual preference.
Sleep difficulties, persistent work-related worry, or difficulty coping with stress call for a different discussion. Counselling, clinical psychology, or other qualified mental-health services may be more appropriate than treating physical tension alone.
These benefits should not be treated as interchangeable merely because they appear under an extended-health policy.
Before comparing appointments, use a decision grid that separates the reason for seeking care from the reimbursement category.
| Decision factor | Physical-health services | Mental-health services |
|---|---|---|
| Primary concern | Muscular discomfort, mobility, physical function | Stress, emotional distress, coping, sleep-related concerns |
| Possible providers | Registered massage therapist, physiotherapist, chiropractor | Eligible counsellor, psychologist, or other covered mental-health professional |
| Coverage to verify | Paramedical limits and approved credentials | Counselling, psychology, and any separate mental-health allowance |
| Additional support | Appropriate clinical assessment and self-management guidance | Potential employer assistance program access |
There is no single Vancouver-wide reimbursement rate or reliable session-price comparison for all these categories. Some policies impose visit caps; others apply reimbursement percentages or category maximums. Compare the actual provider fee with the payment your specific insurer will allow.
Practitioner verification is essential. The CCHPBC’s professional licensing registry allows people to verify the licensing of regulated professionals, including massage therapists and chiropractors in British Columbia. Massage therapists began transitioning to new licence numbers on October 5, 2026, with the transition period extending to March 31, 2027.
For massage claims during that transition, confirm the practitioner’s current details with the clinic and insurer. Professional licensing alone does not guarantee reimbursement. Registered Clinical Counsellor credentials also require verification through the appropriate professional organization rather than this registry.
A useful hybrid approach is to address distinct needs through distinct eligible benefits. Physical treatment may be covered under a paramedical category, while mental-health support may fall under counselling or psychology coverage.
Some employees also have access to an employer assistance program offering short-term support. For example, Health Canada’s federal Employee Assistance Program provides free, confidential counselling for eligible participants in participating federal organizations. Private employer programs vary, so confirm whether your own program is available and how it interacts with insurance limits.
The best financial outcome comes from choosing appropriate care that is actually eligible for reimbursement, rather than selecting appointments solely to exhaust a balance.
The Claim Mistake That Gets Vancouver Wellness Benefits Rejected After 3 Weeks
A workplace wellness claim can be rejected when the receipt lacks required practitioner information, the service or provider is ineligible, a coverage maximum has been reached, or the submission arrives too late. Rejections may take time to appear, but a three-week delay is not universal. Checking eligibility and documentation before paying gives employees a better chance of avoiding preventable problems.
A frequent administrative mistake is leaving a clinic with a receipt that does not contain everything the insurer needs. A payment confirmation alone may not establish the professional credentials, treatment category, or service date required for adjudication.
Before leaving, review the receipt for the following details where your insurer requires them:
- Date of service and service description.
- Practitioner’s full name and applicable professional designation.
- Registration or licence number, where relevant.
- Clinic or provider details required by the plan.
- Amount charged and amount paid.
Do not assume a practitioner is eligible simply because the clinic offers direct billing. Confirm that the professional and service match your policy, especially if the practitioner uses a newly issued registration number.
A rejected claim is not always a lost claim. Read the insurer’s explanation carefully because different rejection reasons call for different responses.
| Rejection message | What it may mean | Practical next step |
|---|---|---|
| Documentation incomplete | Required receipt or practitioner information is missing | Ask for corrected documentation and check resubmission rules |
| Provider or service not eligible | The service or practitioner does not meet plan conditions | Verify the policy and ask for clarification if the decision appears incorrect |
| Maximum reached | The applicable allowance has already been used | Check the benefit calculation and any eligible secondary coverage |
| Submission deadline exceeded | The claim arrived outside the allowed period | Review deadlines and ask whether reconsideration is permitted |
Missing documentation may be correctable if the insurer still accepts additional information. An exhausted maximum or genuinely ineligible treatment normally requires a different resolution. No correction process guarantees payment.
Keep particular track of claims associated with employment changes. Coverage ending after a layoff, resignation, or certain types of leave may affect eligible service dates and the time available to submit outstanding expenses. The precise rules depend on your plan.
The appointment date and claim deadline are separate checks. Receiving treatment within the coverage period does not automatically mean a later submission will be accepted.
A correctly documented claim still needs time to be processed, which is why appointment scheduling deserves attention well before the coverage period ends.
When Should You Book Wellness Appointments in Vancouver to Avoid a 6-Week Waitlist?
Vancouver employees should book needed wellness appointments as soon as they understand their coverage period, remaining allowance, and provider eligibility. Rather than assuming every clinic has a six-week waitlist, check actual availability and work backwards from the last eligible service date. Cancellation lists, nearby municipalities, and virtual appointments can provide alternatives when preferred times are unavailable.
Many employees remember unused coverage only when their plan is approaching renewal. That creates unnecessary pressure to find appointments, verify providers, and submit claims within a shrinking window.
A better approach is to establish the latest date on which treatment can occur, then leave sufficient time for booking, attending, obtaining a valid receipt, and submitting the claim. Your plan may have separate dates for service eligibility and claim submission.
Potentially busy booking periods include the beginning of a calendar-year benefits cycle and the final weeks before December renewals. However, actual availability varies by practitioner, clinic, treatment type, and location. These patterns should not be treated as proof of a standard six-week wait.
If your preferred Vancouver provider has no suitable appointment, consider:
- Joining a cancellation list and asking how short-notice appointments are offered.
- Checking eligible practitioners in Burnaby, Richmond, or New Westminster.
- Asking whether a different appointment time or qualified practitioner is available.
- Checking whether your plan permits virtual counselling or another appropriate remote service.
Do not assume a virtual appointment is covered merely because it is convenient. The service type, practitioner designation, location restrictions, and reimbursement conditions still matter.
Where a treatment plan calls for multiple visits, scheduling appointments across the coverage year can also reduce last-minute pressure. The timing should follow clinical need and professional guidance rather than a desire to spend the remaining maximum.
Set two calendar reminders: one to review benefits before the renewal period and another well ahead of the last eligible service date. Choose reminder intervals that reflect your provider’s actual availability.
Careful scheduling helps protect legitimate reimbursement opportunities, but it cannot solve every problem contributing to workplace stress.
The Perk Trap That Makes Vancouver Employees Accept ‘Wellness’ While Workload Stays Toxic
Wellness benefits can support employees without fixing an unhealthy workload. Massage allowances, counselling coverage, and fitness perks may help people manage specific needs, but they do not replace manageable expectations, sufficient staffing, or reasonable working hours. When the same stress symptoms return because working conditions never improve, using another benefit is only part of the response.
Consider an employee who books massage appointments for recurring shoulder tension and uses counselling sessions to manage persistent stress. Those services may be appropriate and useful. But if the employee continues working excessive hours without adequate breaks, the underlying pressure may remain.
The problem is not that wellness benefits lack value. It is the assumption that providing benefits automatically makes working conditions healthy.
Employees can assess this distinction by asking three questions:
- Do the same symptoms keep returning after temporary relief?
- Are difficult workloads or working conditions contributing to the problem?
- Does the employer offer meaningful ways to address workload concerns beyond individual wellness services?
A recurring pattern does not independently establish a medical diagnosis or prove that work is the sole cause. It can, however, indicate that a conversation about working conditions deserves attention.
Employers may offer wellness programs for employee support, retention, recruitment, or other organizational reasons. There is no basis for assuming every employer deliberately substitutes cheap benefits for adequate staffing or fair workloads.
Use the coverage you have without treating it as compensation for unresolved workplace problems. Counselling or appropriate healthcare may provide support while you assess priorities, communicate concerns, or explore employment options.
Practical next steps might include documenting workload pressures, discussing priorities with a manager, requesting realistic deadlines, or seeking appropriate workplace advice. The right response depends on the circumstances and available protections.
Alongside formal treatment and changes at work, employees may benefit from building recovery time into ordinary routines rather than saving every break for a vacation.
Why Does Mountain Time Recover Vancouver Workers Faster Than Staying ‘Offline’ at Home?
Time outdoors may help Vancouver workers interrupt repetitive work-related thinking, particularly when it includes walking and a change of environment. Research supports potential psychological benefits from nature exposure, but it does not prove that mountain visits restore people faster than resting at home. The practical advantage of nearby natural areas is that meaningful outdoor breaks can fit into an ordinary week.
Switching off a work laptop does not always mean mentally disengaging from work. Someone may remain preoccupied with unfinished tasks, difficult conversations, or the following day’s schedule.
Walking through a natural setting introduces movement, changing surroundings, and opportunities to direct attention away from work-related thoughts. These conditions can make outdoor time a useful complement to other recovery habits.
A PNAS study on nature walks and rumination compared a 90-minute walk in a natural environment with a walk of the same duration in an urban environment. Participants assigned to the nature walk reported less rumination, alongside changes in a specified measure of brain activity.
The study did not compare mountain outings with staying offline at home, and its findings do not demonstrate treatment effectiveness for clinical burnout, anxiety disorders, or depression.
For Metro Vancouver employees, options such as Lynn Canyon and recreational areas around Grouse Mountain or Cypress Mountain provide opportunities to spend time outdoors without organizing a full vacation. Travel time depends on starting point, traffic, transit connections, weather, and the destination selected.
The activity does not need to be strenuous. A manageable walk or short period in a natural setting may be more practical than an ambitious mountain trip, particularly for someone already fatigued.
Some workplace lifestyle or wellness spending accounts may reimburse specified recreation expenses. Eligible items could include certain activities or passes where the employer’s plan explicitly allows them. Outdoor gear, recreation fees, and fitness activities are not universally reimbursable.
Check your spending account’s eligible expense list before purchasing anything. Recreational benefits should not be submitted under a medical treatment category unless the actual service and policy clearly qualify.
Regular access matters more than choosing an impressive destination, so the final step is creating an outdoor routine that realistically fits around work and family commitments.
What to put into practice
- Protect your eligible benefits by checking the real coverage and submission deadlines before making purchases or booking services.
- Choose clinically appropriate support for health needs, while treating recreation and nature time as complementary activities.
- Build manageable recurring breaks into your schedule instead of relying on a future day when nothing else is planned.
How Can Vancouver’s Coastal Mountains Reduce Work Stress Without Taking Full Days Off?
Vancouver employees can make outdoor recovery more practical by choosing short, repeatable activities near home or work instead of waiting for a full day off. A local walk during lunch, an after-work visit to a nearby natural area, or a modest weekend outing can fit different schedules. Pairing these habits with legitimate wellness benefits can help manage costs without confusing recreation with medical coverage.
A reliable routine starts with the time you actually have, not the destination you wish you could visit. For an employee with a short lunch break, a nearby seawall or park may be more useful than a distant mountain trail.
For those with flexible mornings or longer evenings, nearby trails can offer a change of surroundings before or after work. More demanding mountain activities require additional preparation, suitable conditions, and realistic travel allowances.
The following examples are planning options rather than measured itineraries or guaranteed travel times.
| Available window | Possible activity | Effort and planning |
|---|---|---|
| Short lunch break | Walk along an accessible section of the seawall or through a nearby park | Low effort; choose a route close to work |
| Before work | Take a short walk in a neighbourhood green space or accessible ravine | Low to moderate effort; account for commute and daylight |
| After work | Visit an appropriate North Shore natural area when conditions permit | Allow for travel, trail conditions, and a safe return |
| Weekend | Plan a modest outdoor trip around Grouse, Cypress, or another suitable destination | Match the route to fitness, weather, accessibility, and available time |
Consistency is easier when an activity attaches to an existing routine. A recurring weekday walk, a regular park visit after work, or a planned weekend outing creates less scheduling friction than waiting indefinitely for spare time.
Employees with workplace spending accounts can check whether recreation passes, eligible fitness activities, or other specified expenses fall within their policy. Certain employer commuting programs may also help with eligible travel costs, but the existence and scope of such programs must be confirmed individually.
Do not assume outdoor fitness classes are paramedical expenses. A class qualifies for reimbursement only if its actual service category and provider meet the relevant plan rules.
The same financial discipline used for healthcare claims applies here: identify the eligible purchase, confirm the remaining allowance, check documentation requirements, and retain the receipt.
Outdoor time also has a major advantage: many simple activities can be enjoyed without drawing down a workplace benefits balance at all. That allows eligible insurance coverage to remain available for healthcare services when they are needed.
For employees who face mobility, accessibility, childcare, or transportation constraints, a nearby park or shorter accessible route may be a better long-term choice than a mountain destination. There is no requirement to pursue strenuous outdoor recreation to benefit from spending time in nature.
Your next action can be simple: open your plan booklet, identify one appropriate covered service you need, verify its claim rules, and put both the appointment and an affordable outdoor break on your calendar. That creates a practical system for using legitimate benefits while protecting time for recovery.
Can unused workplace wellness benefits be paid out as cash?
Do not assume an unused extended-health allowance can be withdrawn as cash. Such benefits generally reimburse eligible expenses rather than represent a cash balance. Separate employer-funded accounts may have different rules, so check your plan documents for any payout, carryover, or forfeiture provisions.
Can employees use a spouse’s benefits plan after claiming through their own insurer?
Yes, where both policies permit coordination of benefits. An employee’s own workplace plan normally processes their claim first, after which eligible remaining expenses may be submitted to the spouse’s plan. Combined reimbursement cannot exceed the original eligible expense, and additional restrictions may apply.
What happens if a massage therapist’s licence number changes?
British Columbia massage therapists began transitioning to new licence numbers in October 2026. Employees should confirm the practitioner’s current details, ensure the receipt includes the information their insurer requires, and contact the insurer if an administrative mismatch affects a claim. A licence-number change alone does not mean the practitioner has lost professional standing.
Does an employee assistance program reduce regular counselling coverage?
Not necessarily. An employee assistance program may operate separately from extended-health insurance, but arrangements differ across employers. Ask your benefits administrator whether EAP sessions have their own eligibility conditions, session limits, and relationship to your regular counselling maximum.
Can a Vancouver employee claim outdoor recreation expenses through a wellness account?
Possibly, if the employer’s specific lifestyle or wellness spending account includes that expense category. Recreation passes, fitness activities, and equipment-related costs should be checked against the written eligibility rules before purchase. General extended-health insurance should not be assumed to cover recreational activities.